
Understanding Money Beyond the Exchange Rate. Why is the euro worth more than the Brazilian real? Why do some European countries offer different financial opportunities from Brazil? Is it easier to save money, invest, buy a house, or build wealth in Europe?
These questions go far beyond the value of a currency. They involve economic stability, purchasing power, inflation, interest rates, taxation, wages, access to credit, investment opportunities, and the financial habits of individuals and families.
For many Brazilians, the euro represents a stronger currency and the possibility of greater financial security. When traveling to Europe, shopping internationally, or comparing salaries, the difference between euros and reais becomes immediately visible.
However, a higher exchange value does not automatically mean a better financial life.
A person earning €2,000 per month in Europe may struggle with rent and everyday expenses, while someone earning R$8,000 in Brazil may have greater financial flexibility depending on where they live, their housing costs, and their personal circumstances.
The opposite can also be true. A Brazilian household may face expensive credit, limited savings, and rising essential expenses, while a European household benefits from higher disposable income, accessible public services, or more predictable long-term financial planning.
The important distinction is that money must be understood in relation to the economy in which it is earned, spent, saved, and invested.
Europe is not a single economic reality. Germany, France, Spain, Portugal, Ireland, and the Netherlands have different wages, taxes, housing markets, and financial systems. Some European countries, such as Switzerland, do not even use the euro.
Brazil also has substantial regional differences, with different costs of living, employment opportunities, and income levels.
To understand the real differences between the euro and the Brazilian real, we need to examine how these financial systems operate and how they influence people’s daily lives.
1. The Euro and the Real: Why Are Their Values So Different?
The first difference most people notice is the exchange rate.
The euro generally has a substantially higher nominal value than the Brazilian real. This means that one euro can be exchanged for several reais, depending on the current market rate.
But why does this happen?
A currency’s exchange value is influenced by multiple economic forces, including inflation, interest rates, investor confidence, productivity, international trade, government finances, and demand for financial assets denominated in that currency.
The euro is used by a large group of European economies and plays an important role in international trade, investment, and central bank reserves. Its international relevance contributes to demand for the currency.
The real, meanwhile, belongs to an emerging-market economy. Its value can be particularly sensitive to changes in global investment flows, commodity prices, domestic fiscal expectations, political uncertainty, and interest-rate differentials.
These factors help explain why the two currencies can have very different exchange values.
Does the euro have more purchasing power because it is worth more?
Not necessarily.
The exchange rate tells us how much of one currency can be exchanged for another. It does not tell us how much a person can afford in their own country.
Imagine that a Brazilian earns R$6,000 per month and a Spanish worker earns €2,000 per month.
Converting both salaries into the same currency provides one comparison, but it does not establish which person has a better financial life.
We would also need to compare rent, food, transportation, taxes, healthcare, utilities, and the amount each person can save.
The Spanish worker might earn more in international currency terms but spend a large proportion of their income on housing. The Brazilian worker might have lower housing costs, or they might face higher expenses relative to their income.
The result depends on the circumstances.
A strong currency can improve international purchasing power, but domestic financial well-being depends on income, local prices, and economic conditions.
2. Purchasing Power: What Can People Actually Afford?
Purchasing power is one of the most important concepts in the comparison between Brazil and Europe.
It measures the quantity of goods and services that people can buy with their income.
A salary is meaningful only when considered alongside the prices people face.
Purchasing power in Brazil
Brazil offers relatively affordable options for certain locally produced goods and services. Depending on the region, people may find competitive prices for some personal services, locally produced food, and everyday activities.
However, many Brazilian households face pressure from housing costs, private healthcare, education, transportation, and expensive consumer credit.
Imported electronics, international travel, and other products exposed to exchange-rate fluctuations can also be expensive compared with local incomes.
Consequently, even when the nominal price of a product seems reasonable, the amount of work required to pay for it can be significant.
Purchasing power in Europe
Several European economies have higher average wages than Brazil, which can improve the relationship between income and essential expenses.
However, European living costs can be substantial. Rent in cities such as Paris, Amsterdam, Dublin, and Lisbon can consume a large share of monthly earnings. Restaurants, childcare, energy, and other services may also be expensive.
Some European countries provide public services that reduce the need for certain private expenditures, but the extent of these benefits depends on the country, eligibility requirements, and the individual’s situation.
How should purchasing power be compared?
Three questions provide a more useful comparison than exchange rates alone:
- How much of a person’s income goes toward essential expenses?
- How much remains after taxes and monthly bills?
- How much can that person save without relying on credit?
A higher salary does not guarantee greater financial freedom if expenses rise at the same rate.
Likewise, a lower nominal salary can support a comfortable lifestyle when the cost of living is manageable and the person has stable employment.
3. Inflation: How Brazil and Europe Protect the Value of Money
Inflation occurs when the general level of prices rises over time, reducing the purchasing power of money.
Brazil has a history of severe inflation, particularly before the Real Plan introduced the real in 1994. That experience shaped the country’s economic institutions and reinforced the importance of controlling inflation.
European economies have also experienced periods of significant inflation. Energy prices, supply-chain disruptions, geopolitical events, and strong or weak demand can all influence the cost of living.
The important difference is not that Europe has no inflation. It is how inflation develops, how expectations are managed, and how monetary institutions respond.
Inflation and the Brazilian real
Brazil’s Central Bank uses monetary policy to pursue price stability. Its main policy interest rate is the Selic rate.
When inflationary pressures become excessive, higher interest rates can help reduce demand and influence expectations. However, monetary policy also affects borrowing costs, economic activity, employment, and investment.
Inflation can be especially difficult for households whose income does not increase at the same pace as food, housing, transportation, and other essential expenses.
Inflation and the euro
The European Central Bank manages monetary policy for the euro area, with the objective of maintaining price stability.
Countries using the euro share a common monetary policy. This creates important differences from Brazil, which has its own currency and independent monetary policy.
However, the euro area contains economies with different labor markets, productivity levels, housing costs, and economic cycles. A common interest rate does not produce identical results in every member country.
Why does inflation matter to investors?
An investment’s advertised return is not the same as its increase in purchasing power.
Suppose an investment earns 10% over a year while inflation is 5%. Before taxes and fees, the approximate real return is 5%, although the exact calculation is slightly lower.
The same principle applies to investments in euros and reais.
A currency’s reputation cannot replace an assessment of the investment’s actual return after inflation, taxes, and costs.
4. Interest Rates: Why Is Credit Often More Expensive in Brazil?
Interest rates are among the most significant differences between Brazil and many European economies.
Brazil has historically experienced higher nominal interest rates than several advanced European economies. This reflects factors such as inflation expectations, monetary policy, fiscal conditions, perceived credit risk, and the structure of the financial market.
European borrowing costs vary by country and product, and they can increase considerably when monetary policy tightens.
The impact of high interest rates in Brazil
High interest rates can make borrowing expensive for households and businesses.
They affect personal loans, credit card balances, vehicle financing, working capital, and some forms of property financing.
Credit cards and overdraft facilities can be particularly costly when consumers carry unpaid balances. When debt accumulates, a household may spend an increasing share of its income on interest instead of saving or investing.
This can create a difficult cycle: people borrow to cover essential expenses, repayments consume future income, and new borrowing becomes necessary.
Is credit always cheaper in Europe?
No.
Some European mortgage markets have historically benefited from relatively low interest rates, but borrowing costs vary across countries and economic periods. Consumer loans and credit cards can also carry high rates.
Banks assess income, credit history, employment stability, and other factors before approving loans. Access to credit does not guarantee that the terms are affordable.
The relevant comparison is not simply the interest rate in one currency against another. It is the total cost of borrowing relative to income and the borrower’s ability to repay.
The relationship between interest rates and wealth
High interest rates can create attractive nominal yields on certain Brazilian fixed-income investments. At the same time, they can increase the cost of debt for consumers and businesses.
This creates a dual effect.
People with savings may benefit from higher returns on some investments, while people who depend heavily on credit may face greater financial pressure.
A country’s interest-rate environment can therefore affect different households in very different ways.
5. Salaries and Income: Does Earning Euros Mean Being Wealthier?
European salaries are often higher in nominal terms than Brazilian salaries when converted into a common currency.
However, comparing wages requires considering local purchasing power, working hours, taxes, benefits, and employment conditions.
A salary that appears high after conversion may provide only modest disposable income in an expensive city. Conversely, a Brazilian salary can support a different standard of living depending on the region and the individual’s circumstances.
Minimum wages and income differences
European countries use different wage-setting systems. Some have statutory national minimum wages, while others rely more heavily on collective bargaining agreements for certain sectors.
Brazil has a national minimum wage, supplemented by other wage arrangements and, in some cases, regional or occupational rules.
The important difference is not merely the nominal minimum wage. It is what that wage can buy, how many workers earn it, and whether households can cover essential expenses without accumulating debt.
Taxes and take-home pay
Gross salary is not the same as disposable income.
Workers may pay income tax and social contributions, and the amount retained varies according to national rules, income level, household circumstances, and available deductions.
Some European countries have relatively high tax and social contribution rates but also provide public services that reduce certain household costs.
Brazil also has income taxes, social contributions, and consumption taxes that affect households in different ways.
A meaningful salary comparison should therefore use take-home pay and consider the cost of essential services.
Financial security is more than salary
Two workers earning similar amounts can have very different financial outcomes.
One may have affordable housing, no expensive debt, and access to reliable public services. The other may have high rent, family obligations, and significant loan repayments.
The ability to save consistently often matters more for long-term financial security than the headline salary alone.
6. Saving Money: Why Is It Difficult for So Many Families?
Saving is the difference between what a person earns and what they spend, after considering the timing of income and expenses.
This sounds simple, but many households in Brazil and Europe struggle to save because essential expenses consume most of their income.
The Brazilian challenge
Income inequality, expensive consumer credit, housing costs, and the need to pay privately for certain services can make it difficult for some Brazilian households to build reserves.
Unexpected medical expenses, vehicle repairs, job loss, or family emergencies can quickly disrupt a budget.
When there is no emergency reserve, people may depend on credit cards, overdrafts, or personal loans, potentially making future saving even harder.
The European challenge
Higher wages and certain public services may help some European households plan more effectively. Nevertheless, high rents, energy bills, taxes, childcare, and transportation can leave workers with limited disposable income.
In expensive cities, people may earn a salary that appears comfortable from abroad but still struggle to save.
Europe is not financially homogeneous. The cost of living and the relationship between income and expenses can differ significantly between countries and even between cities within the same country.
The savings rate matters
Consider two hypothetical households.
| Household A | Household B | |
|---|---|---|
| Monthly income | R$6,000 | €2,500 |
| Monthly expenses | R$5,400 | €2,350 |
| Monthly savings | R$600 | €150 |
| Share of income saved | 10% | 6% |
These figures are illustrative and are not intended to represent typical salaries or expenses in either region. Because the currencies differ, the amounts saved cannot be directly compared without further adjustments.
However, the example illustrates a useful principle: a household can earn more in nominal terms and still have less room to save as a proportion of its income.
Financial security depends on the relationship between income, expenses, debt, and savings.
7. Banking Systems: Brazil and Europe in the Digital Era
Brazil has a sophisticated banking sector, including traditional banks, digital banks, payment institutions, and financial technology companies.
Europe also has advanced banking systems, but services and payment practices vary between countries.
Both regions have experienced major changes in how people access accounts, transfer money, make payments, and manage personal finances.
Pix and instant payments in Brazil
Pix has transformed payments in Brazil by enabling fast transfers and payments through participating financial institutions.
Its widespread adoption has made it easier for individuals and businesses to receive money, pay bills, and complete transactions without relying exclusively on traditional bank transfers or card payments.
The system has also contributed to the expansion of digital financial services.
Banking and payments in Europe
European banking includes a mixture of traditional institutions, digital banks, card networks, and regional payment infrastructure.
SEPA, the Single Euro Payments Area, facilitates euro transfers among participating countries. Instant payment services are also expanding, although the availability and user experience depend on the country, institution, and payment method.
The European banking landscape is not identical everywhere. A person living in Germany may encounter different practices from someone living in Portugal or Spain.
Does a modern banking system guarantee financial health?
No.
Digital banking improves convenience and can increase competition, but it does not automatically prevent overspending, expensive borrowing, fraud, or poor financial decisions.
A person can manage money through an excellent banking app and still accumulate debt if their expenses consistently exceed their income.
Technology is a tool. Financial stability also requires sustainable income, responsible lending, consumer protection, and informed decisions.
8. Investments: Where Are the Best Opportunities?
Brazil and Europe provide access to different investment markets, products, and economic opportunities.
Neither market is universally better. The appropriate choice depends on investment goals, time horizon, risk tolerance, tax residency, costs, and the currency in which the money will eventually be spent.
Investment opportunities in Brazil
Brazil has an established financial market with several investment categories:
- Government bonds: Including securities available through Tesouro Direto.
- Bank-issued securities: Such as CDBs and other eligible fixed-income products.
- LCIs and LCAs: Certain bank securities associated with real estate and agribusiness financing.
- Stocks: Shares in publicly traded companies.
- Real estate funds: Funds with exposure to property markets and real-estate-related assets.
- Investment funds: Portfolios managed according to different strategies.
Brazilian fixed-income investments can offer attractive nominal yields when interest rates are high. However, investors need to assess taxation, inflation, liquidity, issuer risk, and whether they can hold an investment until maturity.
Higher advertised returns do not automatically mean better investments.
Investment opportunities in Europe
European financial markets provide access to government and corporate bonds, stocks, diversified investment funds, exchange-traded funds, and various retirement savings arrangements.
Investors can obtain exposure to companies operating across multiple countries and industries.
Broad-market ETFs, for example, can offer diversified exposure through a single investment. Nevertheless, diversification does not eliminate market risk, and investment products differ in cost, availability, taxation, and regulatory treatment.
Comparing returns fairly
An investment yielding 12% annually in reais cannot be compared directly with one yielding 5% in euros.
A proper comparison considers:
- Inflation in the relevant currency.
- Taxes and transaction costs.
- Currency movements.
- Liquidity and investment duration.
- Credit risk and market volatility.
- The investor’s future spending needs.
The nominal interest rate is only one part of the calculation.
A high-yield investment in one country may provide a lower real return than expected, while a lower-yield investment in another currency may also lose value after inflation and exchange-rate changes.
The objective is not to choose the currency with the most impressive percentage. It is to build an investment strategy appropriate to the investor’s circumstances.
9. Why Some Brazilians Want to Invest in Euros
Holding assets denominated in different currencies can diversify a person’s financial exposure.
Someone whose income, savings, and investments are all tied to Brazil is highly dependent on the Brazilian economy and the real. International investments can provide exposure to other markets and currencies.
However, buying euros simply because the currency is considered strong is not a complete investment strategy.
Potential advantages of euro exposure
Euro-denominated savings or investments may be useful for people who expect to pay future expenses in euros, such as tuition, accommodation, travel, or relocation costs.
International investment exposure can also reduce dependence on a single country’s financial markets.
What are the risks?
Exchange rates fluctuate.
If the real appreciates against the euro, an investment held in euros may be worth less when converted back into reais, even if its euro value has increased.
International investments can also involve currency conversion costs, brokerage fees, taxes, and reporting obligations.
Furthermore, holding euros in cash does not automatically produce an investment return. If the money earns little or no interest, inflation can gradually reduce its purchasing power.
Match the currency to the goal
Someone planning to move to Spain in two years may want to consider holding part of their relocation budget in euros.
Someone saving for a home in Brazil will generally need to ensure that enough of their money remains available in reais to cover the future purchase and related expenses.
The appropriate currency depends on the goal, timing, and risk tolerance.
10. Taxes: Are Europeans Taxed More Than Brazilians?
Taxation is a major part of the financial comparison between Europe and Brazil, but simple statements about one region having higher taxes can be misleading.
Brazil has federal, state, and municipal taxes. Households encounter taxes through income, consumption, property ownership, and other activities.
European countries also have different layers of taxation, including income taxes, social contributions, value-added taxes, property taxes, and investment-related taxes.
Why European taxes can appear high
Some European countries collect substantial income taxes and social contributions while financing public healthcare, education, pensions, transportation, and other services.
However, the tax burden varies significantly between countries, income levels, and household circumstances.
Not every public service is free, and eligibility rules can determine what residents receive.
What about Brazil?
Brazil’s tax structure is complex, and consumption taxes can affect households across income levels. The effective impact depends on what people earn, what they purchase, and the taxes that apply to their income and activities.
Brazil also finances public services through taxation, although the availability, quality, and accessibility of services differ across locations and categories.
The right way to compare tax systems
The most meaningful comparison considers both sides of the equation:
Income after taxes minus essential living expenses.
It also considers the value and accessibility of public services.
A worker who pays more in taxes but spends less privately on certain essential services may have a different financial outcome from someone who pays less in a particular tax category but must purchase those services independently.
The answer cannot be determined by comparing headline tax rates alone.
11. Housing: Buying or Renting in Brazil and Europe
Housing is one of the largest financial commitments for households in both regions.
The main differences involve property prices, rents, mortgage conditions, taxes, legal protections, and the relationship between housing costs and income.
Housing in Brazil
Buying a home in Brazil often requires a down payment, mortgage financing, transaction expenses, and ongoing maintenance.
Rental costs vary substantially between cities and neighborhoods. In some locations, housing can consume a large portion of a household’s income.
Mortgage interest rates and the terms available to borrowers influence the total cost of ownership.
Housing in Europe
European housing markets vary widely.
Some cities have relatively affordable housing compared with major economic centers, while others face substantial shortages and high rental prices.
In places such as Amsterdam, Paris, Dublin, and parts of Lisbon, housing costs can create considerable pressure even for people earning euros.
Tenant protections, rent regulations, mortgage structures, and homeownership rates differ across countries.
Is buying always better than renting?
Not necessarily.
Buying a property can help build equity over time, but ownership also involves financing costs, maintenance, taxes, and the risk that property values may fall.
Renting can provide flexibility, particularly for people who may move for employment or study. However, renters may face rent increases and uncertainty about future housing costs.
The right decision depends on the local market, available capital, financing conditions, personal circumstances, and expected length of stay.
12. Retirement: How Do Brazil and Europe Prepare People for the Future?
Retirement planning is another important difference between financial systems.
Brazil combines public social security with private pension products and other investment options. European countries generally have public pension systems as well, but the role of employer-sponsored and private retirement savings differs considerably.
Public pensions and financial security
Public pensions can provide a foundation for retirement income, but future benefits depend on eligibility requirements, contribution records, national rules, and the financial sustainability of the system.
Demographic changes, including population aging, create challenges for many countries.
A person who wants a retirement income above the benefits available through public arrangements may need additional savings and investments.
Employer-sponsored pensions
Some European workers benefit from occupational pension arrangements through their employers. Other countries rely more heavily on public pensions or individual savings.
Brazil also has employer-sponsored pension arrangements in certain workplaces, alongside individual private pension products.
The exact benefits depend on the employer, plan rules, contributions, and vesting conditions.
What happens when someone works in both Brazil and Europe?
International careers can create additional questions about pension contributions, eligibility, taxation, and the country in which retirement income will be received.
Applicable social security agreements may affect how contribution periods are considered, but the rules depend on the countries involved.
People who move internationally should verify their specific situation instead of assuming that contributions made in one country automatically produce identical benefits in another.
13. Financial Education and the Culture of Money
Financial education influences how people understand debt, saving, investing, and long-term planning.
However, it is important not to assume that every European is financially literate or that every Brazilian struggles with money management. Financial behavior varies between individuals, families, and communities.
The economic environment can influence people’s decisions, but individual knowledge and habits also matter.
Common financial challenges
People in both regions can struggle with budgeting, expensive debt, impulsive spending, inadequate savings, and a lack of retirement planning.
Some households have limited access to financial education, while others have access to information but find it difficult to apply that knowledge under financial pressure.
The role of financial education
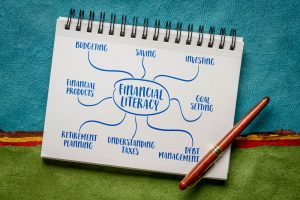
Financial education helps people understand:
- The real cost of borrowing.
- The effects of inflation on savings.
- The difference between nominal and real investment returns.
- The importance of emergency reserves.
- The risks of concentrating all investments in one asset or currency.
- The relationship between present spending and future financial goals.
These skills are useful regardless of the currency in which someone earns their income.
A person who understands how money works is better positioned to compare financial products, identify hidden costs, and make decisions based on long-term objectives rather than immediate convenience.
14. Consumer Credit and the Risk of Household Debt
One of the most important financial differences between Brazil and many European economies is the cost and structure of consumer credit.
Brazilian consumers can face particularly high interest rates on revolving credit card balances and overdrafts. When a household repeatedly uses these products to cover monthly expenses, debt can grow rapidly.
European credit markets also contain expensive borrowing options, but rates, regulations, repayment practices, and consumer protections vary by country and product.
Why debt can become a long-term problem
Imagine that a household’s income is sufficient to pay regular expenses but not enough to cover an unexpected bill.
The household borrows money to cover the shortfall. In the following month, the original expenses return alongside the loan repayment and interest.
If the household still has no financial margin, it may need to borrow again.
Over time, debt repayments can consume a growing share of income, leaving less money available for savings and emergencies.
The difference between productive debt and expensive debt
Borrowing is not automatically harmful.
A loan may help finance education, a business, or a property, depending on the circumstances and repayment terms.
The problem arises when borrowing costs are excessive, the debt does not support a sustainable financial objective, or the borrower cannot reasonably meet the repayment schedule.
A healthy financial environment should make borrowing transparent and support responsible lending rather than encouraging people to depend on expensive credit for ordinary living expenses.
15. Financial Stability: Why Predictability Matters
Financial decisions depend not only on current income but also on expectations about the future.
When people can reasonably anticipate inflation, employment conditions, taxes, and the cost of borrowing, they may find it easier to plan long-term commitments.
Many European economies benefit from established institutions and integration into a large regional market. Nevertheless, they face challenges such as population aging, housing shortages, slow productivity growth in some countries, and economic differences between member states.
Brazil has substantial productive capacity, a large domestic market, significant natural resources, and a sophisticated financial sector. It also faces challenges related to productivity, infrastructure, income inequality, fiscal sustainability, and the cost of credit.
Why predictability affects personal finance
A household considering a mortgage needs to estimate whether future payments will remain affordable.
A business deciding whether to hire workers needs to evaluate demand, financing costs, and economic conditions.
An individual planning retirement needs confidence that savings, contributions, and future expenses can be managed over time.
When economic uncertainty rises, households and businesses may postpone investment or hold more liquid reserves.
However, no economy eliminates uncertainty entirely. European countries can experience recessions, unemployment, and market volatility, just as Brazil can experience periods of growth and improved financial conditions.
16. What Can Brazil Learn From Europe?
The comparison between Brazil and Europe is most useful when it identifies practices that can improve financial security, rather than assuming that one region should copy the other completely.
Several areas are particularly relevant.
Greater economic predictability
Stable inflation expectations and credible institutions help households and businesses make longer-term plans.
Affordable and transparent credit
Clear lending terms, competition, responsible risk assessment, and effective consumer protection can improve access to financing without encouraging excessive debt.
Long-term investment opportunities
Deep capital markets can help businesses raise funds and give households more opportunities to invest across different asset classes.
Financial education
People need accessible information about interest rates, investment risks, taxation, and the long-term effects of borrowing.
Productivity and income growth
Sustainable productivity improvements can support higher wages, stronger businesses, and better living standards.
Effective public services
Accessible healthcare, education, transportation, and social protection can reduce the financial pressure on households and help people manage major life risks.
Brazil’s economic structure and social needs differ from those of European countries. The goal should be to adapt useful practices to Brazilian circumstances while strengthening the country’s own advantages.
17. What Can Europe Learn From Brazil?
The comparison also works in the opposite direction.
Brazil has developed financial innovations and services that offer useful lessons for other economies.
Pix and the transformation of payments
Pix has changed how individuals and businesses transfer and receive money in Brazil. Its widespread adoption demonstrates the potential of accessible instant payments to transform everyday transactions.
Other countries developing payment infrastructure can learn from Brazil’s experience with adoption, convenience, and digital access.
Financial technology and competition
Brazil’s fintech sector has expanded access to digital banking, payments, and other financial services.
Competition between traditional financial institutions and newer providers can encourage innovation, improve customer experiences, and put pressure on costs.
Financial inclusion
Digital services can help people who previously faced barriers to accessing formal financial products participate more fully in the economy.
However, financial inclusion should be accompanied by consumer protection, privacy safeguards, and responsible lending practices.
Adaptability and entrepreneurship
Businesses operating in complex economic environments often develop practical ways to manage costs, reach customers, and respond to changing conditions.
These experiences can provide useful lessons for entrepreneurs and financial institutions in other countries.
Economic development is not a one-way process in which emerging economies only learn from richer countries. Every financial system has strengths, weaknesses, and lessons worth sharing.
18. Is It Better to Live in Brazil or Europe Financially?
There is no universal answer because the result depends on the country, city, profession, salary, family situation, and personal priorities.
A person working in a high-paying profession in Germany may have very different opportunities from someone earning a modest salary in Portugal.
Likewise, a Brazilian professional with a strong income and affordable housing may have a different financial experience from someone living in a major city while paying high rent and expensive loan installments.
Factors that influence the comparison
Income potential: How much can a person realistically earn in their profession?
Housing: How much of the income will be spent on rent or mortgage payments?
Taxes and contributions: What will the take-home income be?
Public services: Which services are accessible, and how much will they reduce private expenses?
Credit costs: How expensive will borrowing be if necessary?
Employment opportunities: How stable is the job market in the relevant profession?
Family and social networks: Will moving reduce existing support or create additional costs?
Long-term plans: Does the person intend to remain in the country, return to Brazil, or move elsewhere?
A move to Europe can improve someone’s financial circumstances, but it can also create new expenses and uncertainties. The decision should be based on a realistic budget rather than the exchange rate alone.
19. Euro vs. Real: Which Currency Is Better for Saving and Investing?
The answer depends on the purpose of the money.
For someone who lives in Brazil and expects to spend their savings locally, investments denominated in reais may be appropriate for many short-term expenses.
For someone planning to study, relocate, or buy something in the euro area, holding part of their future budget in euros may help reduce the risk of an unfavorable exchange-rate movement before the expense occurs.
For long-term investors, diversification across international markets and currencies may also be worth considering.
Matching currency to financial goals
| Financial objective | Main consideration |
|---|---|
| Emergency reserve in Brazil | Liquidity and expenses in reais |
| Education or relocation in Europe | Future expenses in euros |
| Long-term wealth building | Diversification, risk, fees, and taxes |
| Retirement | Expected residence, pension benefits, and future expenses |
| International travel | Exchange costs and timing of spending |
The objective is not to hold the currency with the highest exchange value. It is to make sure the currency and investments support the goals for which the money is intended.
20. Common Myths About the Euro and the Brazilian Real
Myth 1: Everyone who earns euros is wealthy
A salary in euros does not guarantee financial security. Housing, taxes, family responsibilities, and local income levels can leave some European households under substantial pressure.
Myth 2: The real is worthless because one euro buys several reais
The exchange rate does not measure the complete value of a currency within its domestic economy. Local wages, prices, and purchasing power matter.
Myth 3: Europe does not experience inflation
European households can experience significant price increases. A currency’s international strength does not eliminate inflation or protect every consumer from rising costs.
Myth 4: Brazilian investments are always worse
Investments carry different risks and returns. Brazilian government securities, European bonds, stocks, and bank deposits should be assessed according to their individual characteristics rather than their country of origin alone.
Myth 5: Investing in euros guarantees higher returns
Exchange-rate movements can increase or reduce returns when measured in another currency. International investments can lose value, and the euro itself can depreciate against the real.
Myth 6: High interest rates always make a country more attractive
High rates can offer attractive nominal yields, but they may also reflect inflation risks, uncertainty, or other economic pressures. Investors must understand why the yield is high.
Myth 7: Moving to Europe automatically improves financial life
Relocation can create opportunities, but it also involves housing, transportation, documentation, taxes, employment uncertainty, and other costs. The outcome depends on the complete financial picture.
21. Frequently Asked Questions About the Euro and the Brazilian Real
Why is the euro generally worth more than the real?
The exchange rate reflects international demand for currencies, interest-rate differences, inflation expectations, economic conditions, investor confidence, and other factors. No single explanation accounts for the entire difference.
Is it better to save in euros or reais?
It depends on where the money will be spent, the time horizon, and the available investment options. Savings intended for Brazilian expenses generally need to be accessible in reais, while future euro expenses may justify holding some money in euros.
Is the cost of living lower in Brazil than in Europe?
Some goods and services may be less expensive in Brazil, but costs vary by city, lifestyle, and income. A useful comparison considers purchasing power rather than nominal prices alone.
Are interest rates lower in Europe?
They have often been lower than Brazilian rates, but this is not guaranteed. Rates vary by country, period, borrower, and financial product.
Can Brazilians invest in European markets?
Brazilian residents can generally obtain international investment exposure through eligible financial products and providers, subject to applicable regulations, fees, taxation, and reporting obligations. The appropriate route depends on each investor’s circumstances.
Does the euro protect savings from inflation?
No. The euro can lose purchasing power when prices rise. The same is true of the real and other currencies. The relevant question is how the return on savings compares with inflation and costs.
What is the biggest financial difference between Brazil and Europe?
There is no single difference that explains everything. Interest rates, income levels, purchasing power, public services, taxes, housing costs, and economic conditions all contribute to the financial experience of households.
Conclusion: The Real Difference Is More Than the Currency
The euro and the Brazilian real represent two different economic environments, but the exchange rate alone cannot explain the financial differences between Europe and Brazil.
The comparison involves purchasing power, inflation, wages, credit costs, taxes, investment opportunities, housing, retirement, and the economic conditions that determine how easily people can build financial security.
Many European economies benefit from established institutions, international market integration, and public services that can reduce certain household expenses. Brazil, meanwhile, has a sophisticated financial sector, a dynamic fintech industry, a large domestic market, significant productive capacity, and payment innovations such as Pix.
Both regions face challenges, and neither currency guarantees prosperity.
For individuals, the most useful approach is to evaluate money in the context of everyday life: how much is earned, how much is spent, how much remains after essential expenses, and how effectively savings can support future goals.
For businesses and governments, long-term financial progress depends on productivity, stable prices, responsible credit markets, investment, and economic opportunities that reach a broad share of the population.
The euro may buy several reais, but a higher exchange value is only one part of the financial picture. True financial strength is reflected in purchasing power, economic opportunity, financial stability, and the ability to turn income into lasting security.